
A business can be profitable and still run short of cash.
Customers may take 30, 60 or 90 days to pay, while salaries, rent, suppliers, utilities and taxes have to be paid much sooner. Inventory may also consume cash before it generates revenue.
This gap between money going out and money coming in is where working capital finance becomes important.
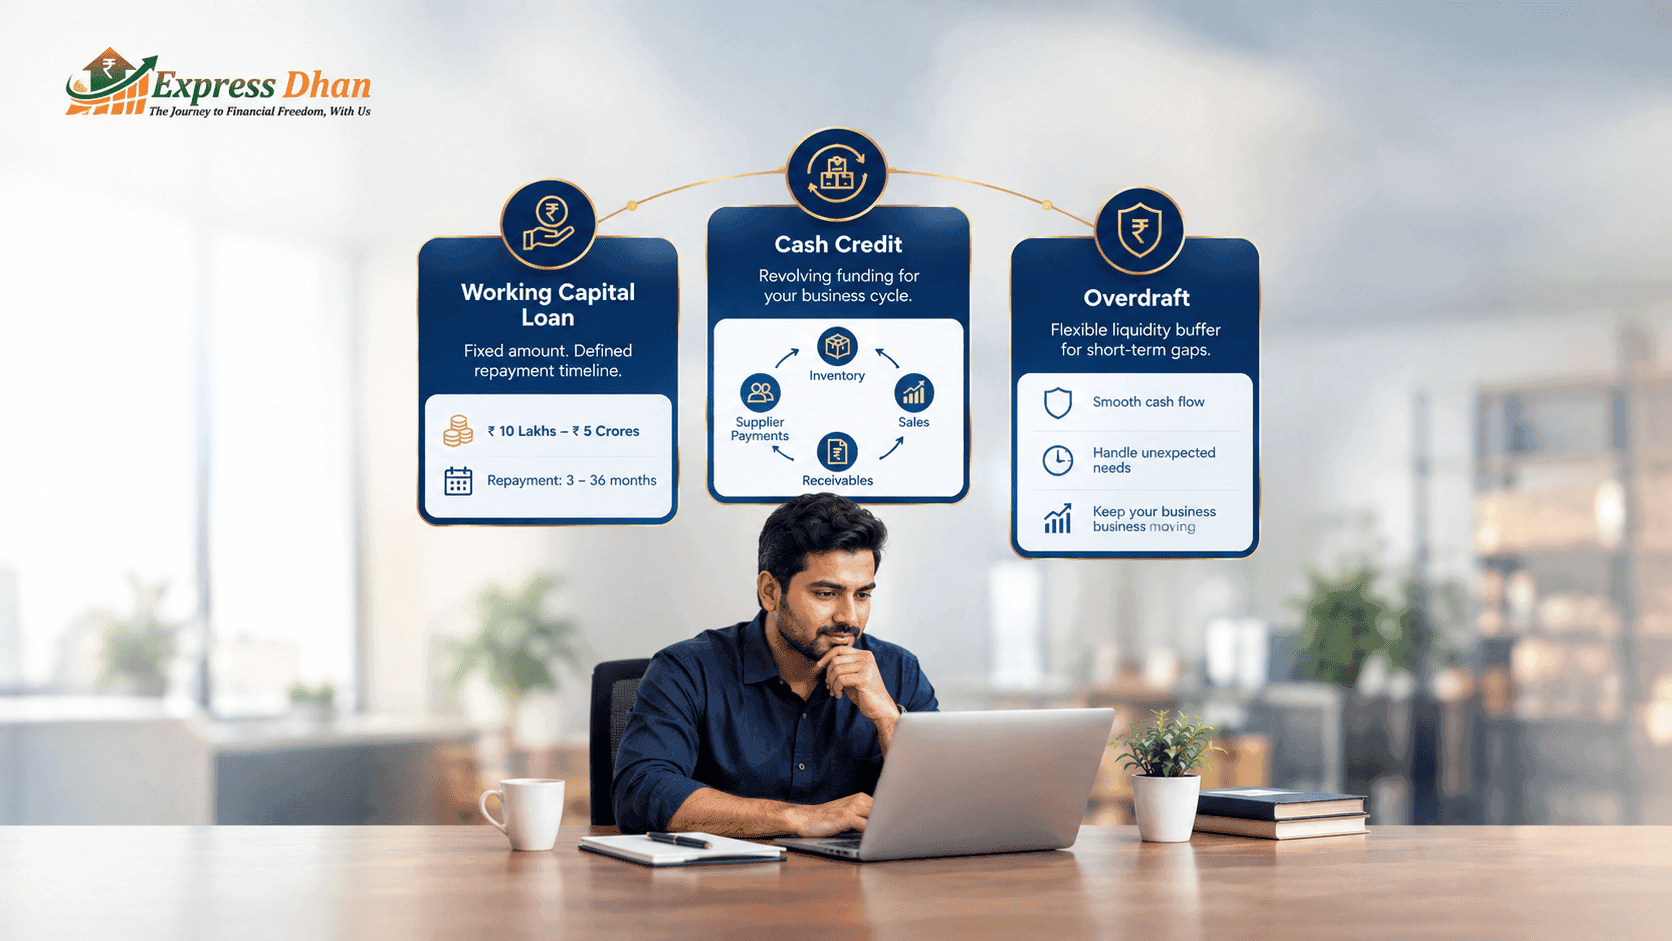
For Indian businesses, three commonly discussed options are:
Working Capital Loan
Cash Credit (CC)
Overdraft (OD)
Although all three can help manage short-term funding requirements, they are not interchangeable.
A working capital loan generally provides a defined amount for a specified period. Cash credit provides a revolving borrowing limit, usually linked to the business's working-capital cycle and, depending on the facility, drawing-power or security requirements. An overdraft allows the borrower to withdraw beyond the available balance or up to an approved limit, with the exact structure depending on the lender and account arrangement.
The right choice depends on why you need the money, how frequently you need it, how quickly cash comes back into the business, and how much flexibility you require.
What Is Working Capital Finance?
Working capital represents the funds a business needs to operate its day-to-day activities.
A simplified calculation is:
Working Capital = Current Assets − Current Liabilities
For lending purposes, however, the question is usually more practical:
How much short-term funding does the business need to keep operating smoothly until its operating cash comes back?
Consider a distributor that purchases ₹20 lakh of inventory.
It sells that inventory to customers but allows them 45 days to pay. During those 45 days, the business still has to pay suppliers, employees and other expenses.
The business may therefore have strong sales but temporarily insufficient cash.
Working capital finance can bridge this timing mismatch.
Common working capital requirements include:
Purchasing inventory
Paying suppliers
Funding receivables
Meeting payroll
Managing seasonal demand
Funding confirmed orders
Covering temporary cash-flow gaps
Maintaining operating liquidity
The important point is that working capital finance is generally intended to support the operating cycle, rather than permanently fund long-term assets.
Working Capital Loan vs Cash Credit vs Overdraft: Quick Comparison
Feature | Working Capital Loan | Cash Credit | Overdraft |
|---|---|---|---|
Basic structure | Defined loan | Revolving credit facility | Revolving withdrawal facility |
Disbursement | Usually predetermined | Draw as required within limit | Draw as required within limit |
Repayment | Structured | Flexible within facility terms | Flexible within facility terms |
Interest | Generally on outstanding loan amount | Generally on amount utilized | Generally on amount utilized |
Flexibility | Moderate | High | High |
Best suited for | Predictable funding requirement | Regular working-capital cycle | Short-term liquidity gaps |
Repeated withdrawals | Usually not the primary feature | Yes | Yes |
Limit renewal/review | Depends on lender/product | Common | Depends on lender/product |
Typical security | Depends on product | Often linked to business assets/security | Depends on facility |
Ideal for | Defined requirement | Ongoing operating cycle | Temporary cash-flow needs |
The exact terms, pricing, collateral requirements and documentation differ between lenders.
So the comparison should be used as a decision framework, not as a universal rule.
What Is a Working Capital Loan?
A working capital loan is a financing facility designed to provide funds for business operating requirements.
Unlike a revolving facility where the borrower can repeatedly draw and repay within an approved limit, a conventional working capital loan generally provides a defined amount with a predetermined repayment structure.
For example, a business may borrow:
₹30 lakh for 24 months
The borrower receives the funds and repays the facility according to the agreed schedule.
This structure can be useful when the business knows approximately how much funding it needs and for how long.
When a Working Capital Loan Makes Sense
It may be suitable when:
You have a clearly defined funding requirement.
You need a substantial amount upfront.
Your cash requirement is relatively predictable.
You prefer scheduled repayments.
You do not need to continuously redraw funds.
The funding requirement has a defined duration.
Example
A manufacturer receives a large confirmed order and needs ₹40 lakh of additional working capital to purchase raw materials and fulfil the order.
If the requirement is clearly defined and the business expects collections after completing the order, a working capital loan may be more appropriate than maintaining a large revolving facility.
What Is Cash Credit?
Cash Credit, commonly called CC, is a revolving working-capital facility that allows an eligible business to draw funds up to an approved limit.
The borrower does not necessarily have to use the entire sanctioned amount.
For example:
Approved CC limit: ₹1 crore
If the business currently needs only ₹35 lakh, it may use ₹35 lakh, subject to the facility's terms and drawing availability.
As customers pay and the business's cash position improves, the outstanding borrowing can reduce. The business can then draw again when working-capital needs increase, subject to the lender's rules.
This makes CC particularly useful for businesses with recurring and fluctuating working-capital requirements.
How Cash Credit Works
Imagine a distributor with:
₹5 crore annual turnover
45-day customer credit
30-day supplier credit
Regular inventory purchases
Its working-capital requirement changes throughout the month.
It may need ₹20 lakh one week and ₹50 lakh a few weeks later.
A revolving CC facility can provide more flexibility than repeatedly applying for separate loans.
The lender may determine the sanctioned limit using its assessment methodology, which can consider factors such as:
Turnover
Receivables
Inventory
Payables
Banking activity
Financial statements
Existing liabilities
Business cycle
Credit profile
Depending on the facility, the amount that can actually be drawn may also be subject to drawing-power calculations and security conditions.
What Is an Overdraft?
An overdraft allows a borrower to withdraw more money than the available account balance, up to an approved limit.
For example:
Available balance: ₹5 lakh
Approved overdraft limit: ₹20 lakh
The business may be able to use the additional funds within the approved terms.
An OD can be particularly useful when the business experiences short-term and unpredictable cash-flow gaps.
The exact structure varies significantly.
An overdraft may be:
Linked to a current account
Secured against an asset
Supported by deposits or other collateral
Approved based on business financial strength
Structured as a business credit facility
Therefore, "overdraft" describes a facility structure rather than one identical product offered by every lender.
Cash Credit vs Overdraft: What Is the Difference?
CC and OD are often confused because both can provide flexible access to funds.
The difference is usually in the way the facility is structured and secured.
Cash Credit
CC is traditionally associated with financing a business's working-capital cycle and may be assessed against business assets such as inventory and receivables, depending on the lender and facility.
Overdraft
OD is generally structured around an approved withdrawal limit and can be secured or unsecured depending on the product.
For example, an OD may be offered against:
Property
Fixed deposits
Securities
Other acceptable collateral
Business financial strength
The exact terms depend on the lender.
Therefore, businesses should compare the actual facility agreement, not simply the labels "CC" and "OD."
Working Capital Loan vs Cash Credit
The key difference is predictability versus flexibility.
A working capital loan can be more appropriate when you know the amount and approximate duration of your requirement.
Cash credit can be more suitable when the funding requirement repeatedly rises and falls with the operating cycle.
Example
A wholesaler requires approximately ₹60 lakh throughout the year, but the actual requirement changes every month.
A CC facility may provide more flexibility.
A business that needs ₹60 lakh for a specific six-month requirement with a predictable repayment source may prefer a structured working capital loan.
Working Capital Loan vs Overdraft
The same principle applies when comparing a working capital loan with an overdraft.
A loan generally creates a structured repayment obligation.
An overdraft can provide greater flexibility for short-term cash requirements.
Choose a structured loan when:
The requirement is clearly defined.
You need the funds upfront.
You can forecast repayment.
You want a predetermined repayment schedule.
Consider an overdraft when:
Cash requirements are unpredictable.
You need temporary liquidity.
You expect frequent inflows.
You want to pay interest based on actual utilization, subject to facility terms.
Which Facility Is Best for Seasonal Businesses?
Seasonal businesses often have highly uneven cash requirements.
Consider a business selling products around:
Diwali
Wedding season
School reopening
Agricultural cycles
Holiday periods
Industry-specific peak seasons
The business may purchase large amounts of inventory before the season and collect most of its revenue afterward.
A fixed loan may provide the required funding, but a flexible revolving facility can sometimes better match the changing requirement.
Example
A ₹10 crore business may require:
₹20 lakh working capital in January
₹35 lakh in March
₹80 lakh before peak season
₹30 lakh after collections begin
A revolving facility can potentially align better with such fluctuations than borrowing the maximum amount permanently.
The right choice ultimately depends on the lender's product structure and the business's financial profile.
Which Option Is Better for Inventory Financing?
If inventory is the main source of the funding requirement, CC can often be considered because working-capital facilities can be designed around the business's operating cycle.
But inventory alone does not determine eligibility.
Lenders can also evaluate:
Inventory turnover
Stock quality
Obsolescence risk
Sales velocity
Customer demand
Supplier terms
Receivable cycle
A company with ₹2 crore of inventory is not automatically entitled to ₹2 crore of working-capital finance.
The lender needs to determine how much of that inventory genuinely supports productive business activity.
Which Option Is Better for Managing Receivables?
Businesses selling on credit frequently face a timing gap:
Sale today → Invoice raised → Customer pays later
Suppose a business generates ₹1 crore in monthly sales but customers take 60 days to pay.
A significant amount of cash can remain tied up in receivables.
Working-capital facilities can help bridge this gap, subject to lender assessment.
However, businesses should not use borrowing to permanently compensate for poor collections.
If receivable days continue increasing, the underlying problem may be customer-credit discipline rather than insufficient financing.
How Lenders Decide Your Working Capital Limit
A lender may consider several financial indicators before deciding the appropriate facility and limit.
Turnover
Higher business turnover can indicate greater operating scale, but turnover alone does not establish repayment capacity.
Operating Cycle
The lender may evaluate how long money remains tied up in:
Inventory → Sales → Receivables → Cash
The longer the cycle, the greater the potential working-capital requirement.
Profitability
A business should demonstrate sufficient earnings and cash generation to support its financial obligations.
Banking Turnover
Actual banking transactions can help demonstrate whether reported business activity is supported by real cash flows.
Existing Debt
Existing loans and repayment obligations reduce the amount of additional borrowing the business may comfortably support.
GST and Financial Records
Consistent financial and tax records can make it easier to establish the scale and stability of the business.
Credit History
Past repayment behavior can influence lender confidence and the terms offered.
A Simple Working Capital Example
Consider a distributor with the following figures:
Annual sales: ₹12 crore
Average inventory: ₹2 crore
Receivables: ₹1.5 crore
Payables: ₹1 crore
A simplified net working-capital position is:
₹2 crore + ₹1.5 crore − ₹1 crore = ₹2.5 crore
But that does not mean the business automatically needs a ₹2.5 crore loan.
The business may already fund part of its working capital through:
Internal cash
Supplier credit
Customer advances
Existing banking facilities
The lender therefore evaluates the funding gap, not simply the gross value of current assets.
This distinction is critical when estimating the appropriate borrowing requirement.
Cost Matters: Don't Compare Only Interest Rates
Businesses often make the mistake of comparing facilities solely by the advertised interest rate.
The actual cost can include:
Interest
Processing fees
Renewal charges
Documentation charges
Valuation charges
Legal charges
Insurance requirements
Penal charges
Commitment or other facility-specific charges
For revolving facilities, another important factor is utilization.
A facility with a higher nominal rate may still be practical if the business uses it only occasionally, while a lower-rate facility may become expensive if it requires additional fees or has restrictive terms.
Always compare the total cost and actual usage pattern.
The Flexibility Advantage of Revolving Facilities
One major advantage of CC and OD facilities is that the business may not need to borrow the entire sanctioned limit continuously.
Suppose the approved limit is ₹1 crore.
The business may use:
₹20 lakh during one period
₹50 lakh during another
₹80 lakh during peak demand
This can be more efficient than taking a ₹1 crore fixed loan when the business does not need the full amount at all times.
However, the benefit depends on the lender's pricing and facility conditions.
When a Working Capital Loan May Be Better
A working capital loan can make more sense when:
You have a defined requirement
For example, you need ₹50 lakh to support a specific expansion cycle.
Your cash requirement is predictable
You know when the money will be required and how it will be repaid.
You prefer structured repayment
Fixed or predetermined repayment schedules can make financial planning easier.
You don't need repeated withdrawals
If the requirement is a one-time working-capital need, maintaining a revolving facility may not be necessary.
When Cash Credit May Be Better
CC can be considered when:
Your operating cycle is continuous
You regularly buy inventory, sell products and collect customer payments.
Your cash requirement changes
The amount required varies throughout the month or year.
You need recurring access to working capital
You want a facility that can be used, repaid and utilized again within the approved terms.
Inventory and receivables drive your funding requirement
The facility is intended to support the normal operating cycle.
When an Overdraft May Be Better
OD can be useful when:
The cash-flow gap is temporary
You expect money to arrive shortly but need liquidity immediately.
You need flexibility
Your funding requirement cannot be predicted precisely.
You have acceptable collateral
Some OD products are structured against assets or deposits.
You want a facility for occasional liquidity needs
An OD may be more appropriate than maintaining a large permanent working-capital facility.
Common Mistakes Businesses Make
Borrowing more than the operating cycle requires
A larger limit is not automatically better.
Excess borrowing can increase interest costs and encourage inefficient capital allocation.
Using working capital for long-term assets
Buying machinery, property or other long-term assets with short-term working-capital funding can create a maturity mismatch.
Long-term assets generally need financing with an appropriate repayment horizon.
Ignoring receivable collection
If customers consistently delay payment, increasing the borrowing limit may only mask the underlying problem.
Choosing based only on the sanctioned amount
A ₹1 crore facility is not necessarily better than a ₹50 lakh facility if the business only needs ₹40 lakh.
Not reviewing facility terms
Interest rate is only one component of financing cost.
Mixing personal and business borrowing
Poor financial separation can make cash-flow management and lender assessment more difficult.
A Practical Decision Framework
Use this simple framework before choosing a facility.
Choose a Working Capital Loan if:
Your requirement is defined + funding is needed upfront + repayment can be planned.
Consider Cash Credit if:
Your requirement is recurring + utilization fluctuates + inventory/receivables drive the cash cycle.
Consider an Overdraft if:
Your requirement is short-term or unpredictable + you need flexible access to liquidity.
The final choice should also consider:
Interest rate
Processing charges
Collateral
Renewal requirements
Drawing conditions
Repayment terms
Facility tenure
Prepayment rules
Documentation
Lender-specific conditions
What Should an MSME Owner Calculate Before Applying?
Before approaching a lender, prepare these numbers:
1. Annual turnover
Know your current and recent historical sales.
2. Average monthly sales
This helps explain the scale of your operating cycle.
3. Receivable days
How long do customers typically take to pay?
4. Inventory days
How long does inventory remain before being sold?
5. Payable days
How much supplier credit does the business receive?
6. Existing borrowing
List current loans, CC limits, OD facilities and other liabilities.
7. Monthly debt obligations
Calculate existing EMI and interest commitments.
8. Peak working-capital requirement
Identify the months when the business needs the most funding.
9. Internal contribution
Determine how much working capital can be funded from the business's own resources.
10. Actual funding gap
The final requirement should reflect the amount genuinely needed after considering internal cash and supplier/customer terms.
Can One Business Use More Than One Facility?
Potentially, yes.
A business may have different financing requirements that need different structures.
For example:
A term loan for machinery
Cash credit for inventory and receivables
An overdraft for temporary liquidity
However, combining multiple facilities increases financial complexity and total obligations.
The lender will also consider the business's overall borrowing exposure.
The objective should therefore be matching each funding requirement with the appropriate financing structure, rather than collecting as many credit facilities as possible.
Working Capital Finance Should Follow the Business Cycle
The best facility is not necessarily the one with the largest limit or the lowest advertised rate.
It is the facility that matches how cash actually moves through the business.
If your business repeatedly experiences:
Purchase → Inventory → Sale → Receivable → Collection
then a revolving working-capital facility may be appropriate.
If you have a clearly defined temporary funding requirement, a structured loan may be more suitable.
If your cash-flow gaps are occasional and short-lived, an overdraft may provide the flexibility you need.
The key is to understand your operating cycle before choosing the financing product.
Final Verdict: Which One Is Right for Your Business?
There is no universal winner between a working capital loan, cash credit and overdraft.
Each solves a different cash-flow problem.
Working Capital Loan: Better suited to a defined and relatively predictable funding requirement.
Cash Credit: Better suited to recurring working-capital needs that fluctuate with inventory, sales and receivables.
Overdraft: Better suited to flexible, short-term liquidity requirements, depending on the facility structure.
For an MSME owner, the right starting point is not:
"Which loan can I get?"
It is:
"Where exactly is my business's cash getting stuck, and for how long?"
Once that is clear, choosing the appropriate financing structure becomes much easier.
A business with healthy sales but slow collections may need working-capital support. A seasonal distributor may need a revolving facility. A business facing an occasional short-term gap may benefit from an overdraft.
Before accepting any facility, compare the total cost, repayment obligations, collateral requirements and operational flexibility.
The best business finance is not the biggest facility. It is the facility that fits the cash-flow cycle of the business without creating an unnecessary repayment burden.