
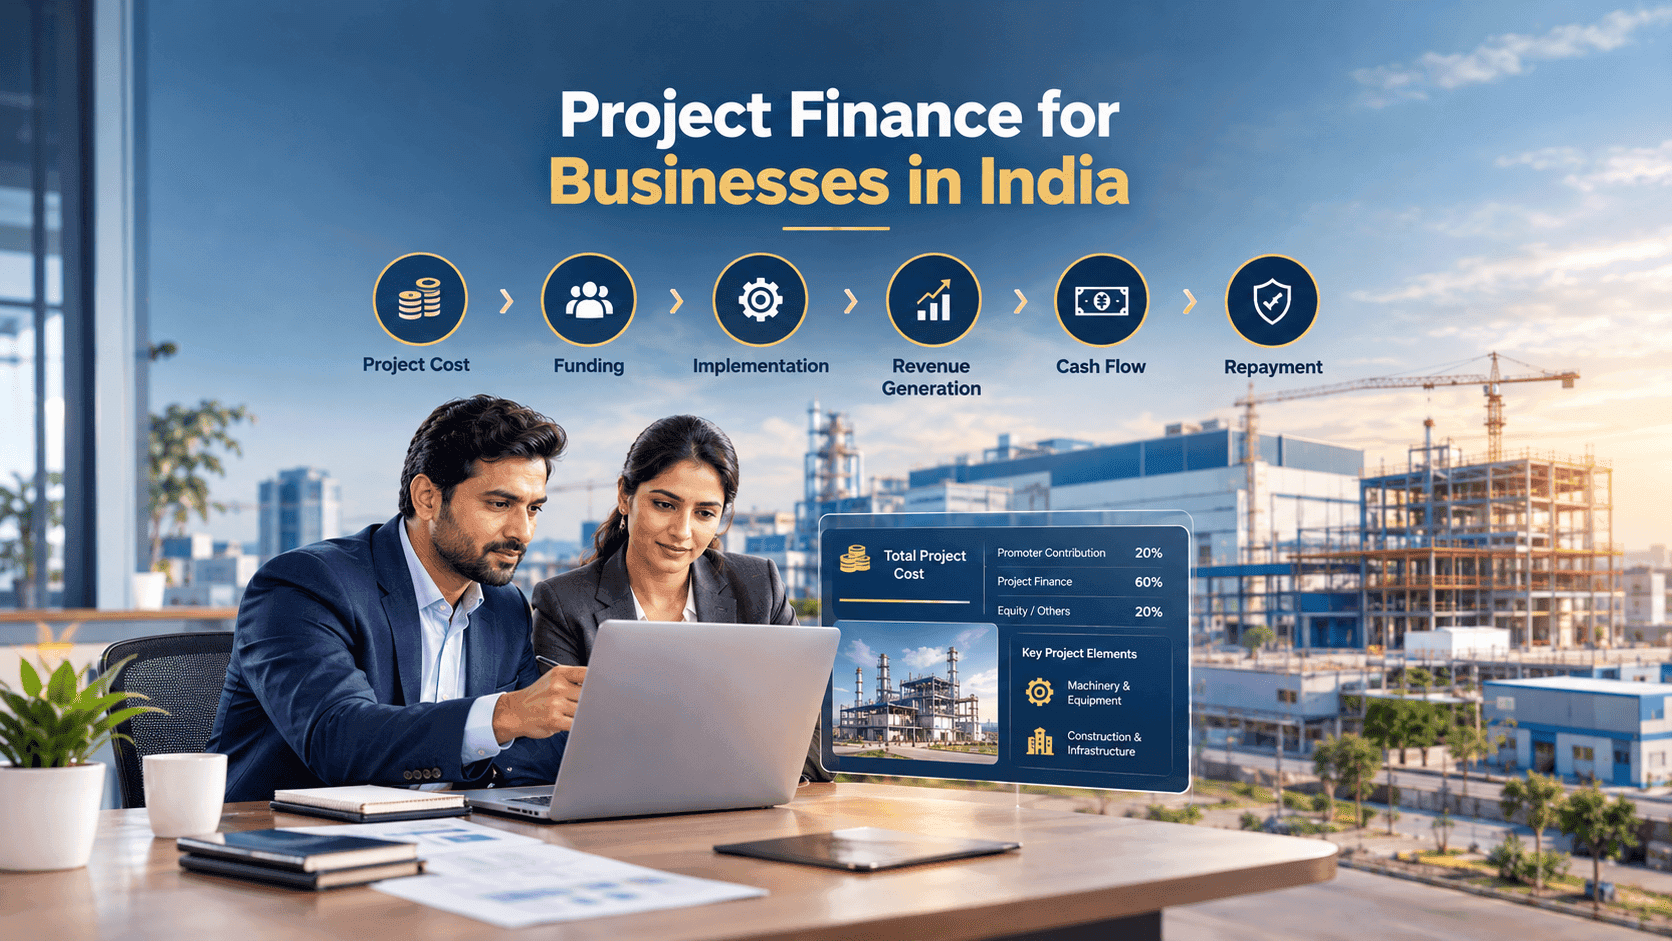
Project finance is used when a business needs substantial funding to establish, expand or modernize a project and repay the borrowing primarily through the project's future cash flows.
Unlike a conventional business loan used for general operating expenses, project finance is closely connected to a specific investment plan. The lender evaluates not only the borrower's existing financial position but also whether the proposed project is technically feasible, financially viable and capable of generating enough cash to service the debt.
For an Indian business, this can apply to projects such as:
Setting up a new manufacturing plant
Expanding an existing production facility
Establishing a warehouse or logistics facility
Developing a commercial project
Setting up renewable-energy capacity
Purchasing and installing large-scale machinery
Expanding a healthcare or hospitality facility
Establishing a new business unit
Modernizing an existing industrial facility
The structure can involve term loans, promoter contribution, working-capital facilities and, depending on the project, other sources of funding.
The most important principle is simple:
A lender is not only financing what the business wants to build. It is assessing whether the project can generate enough sustainable cash flow to repay the financing.
What Is Project Finance?
Project finance is a structured form of long-term financing used to fund a specific business or infrastructure project.
The financing requirement is generally built around the project's:
Total project cost
Promoter contribution
Debt requirement
Expected revenue
Operating expenses
Projected cash flows
Repayment capacity
Implementation timeline
Security structure
Financial viability
For example, suppose an established manufacturing company plans to build a new production facility costing ₹20 crore.
The proposed funding structure could include:
Promoter contribution: ₹6 crore
Project finance debt: ₹12 crore
Other eligible funding: ₹2 crore
The lender would not simply look at the ₹12 crore borrowing request.
It may examine the entire project:
Land → Construction → Machinery → Installation → Commercial Operations → Revenue → Cash Flow → Debt Repayment
This is what makes project finance different from simply requesting a larger business loan.
Project Finance vs Business Loan
The terms are sometimes used interchangeably, but the underlying assessment can be different.
Factor | Project Finance | Conventional Business Loan |
|---|---|---|
Primary purpose | Fund a specific project | General business requirement or defined purpose |
Assessment | Project + borrower | Primarily borrower/business |
Repayment source | Often linked strongly to project cash flows | Existing business cash flows |
Project appraisal | Usually significant | Depends on product |
Technical feasibility | Important for project-driven borrowing | Usually less central |
Promoter contribution | Often important | Depends on product |
Financial projections | Detailed projections commonly required | May be simpler |
Implementation schedule | Usually relevant | May not be central |
Security | Depends on structure | Depends on facility |
Tenure | Often longer-term | Depends on product |
A conventional business loan may be suitable for working capital, equipment, expansion or other defined needs.
Project finance becomes particularly relevant when the investment is large enough that the lender needs to understand the economics of the project itself.
What Types of Projects Can Be Financed?
Project finance is not limited to one industry.
The suitability depends on the lender, project structure, risk profile and financial viability.
Manufacturing Projects
Examples include:
New manufacturing units
Production-line expansion
Capacity expansion
Plant modernization
Industrial facilities
Processing units
Infrastructure-Related Projects
Depending on the lender and applicable financing framework, projects may include infrastructure assets such as:
Roads
Renewable energy
Utilities
Logistics infrastructure
Industrial infrastructure
Commercial Projects
Businesses may seek financing for:
Warehousing facilities
Commercial establishments
Hotels
Hospitals
Educational facilities
Other income-generating assets
Expansion Projects
An existing business may use project finance to:
Add production capacity
Enter a new location
Establish a new facility
Install large machinery
Modernize an existing plant
Develop a new revenue-generating business unit
The key question is not simply whether the project belongs to a particular industry.
It is:
Does the proposed project have a credible business model and sufficient repayment capacity?
How Project Finance Is Structured
A project finance proposal generally starts with the total project cost.
A simplified structure might look like this:
Total Project Cost
₹25 crore
↓
Promoter Contribution
₹7.5 crore
↓
Debt Requirement
₹17.5 crore
↓
Project Implementation
Land + Construction + Machinery + Installation + Pre-operative Expenses
↓
Commercial Operations
Production → Sales → Collections
↓
Project Cash Flow
Operating Cash Flow → Debt Servicing
The actual structure varies by project.
A lender may also consider:
Existing business contribution
Equity or quasi-equity
Term debt
Working-capital requirement
Subsidies or eligible incentives
Internal accruals
Other permitted funding sources
The funding structure needs to ensure that the project has enough capital to reach commercial operations without creating an unsustainable debt burden.
What Does a Lender Evaluate?
Project finance requires a broader assessment than simply checking turnover and credit score.
A lender may evaluate five major areas:
Promoter and borrower strength
Technical feasibility
Financial viability
Market and business risk
Security and repayment structure
Let's examine each.
1. Promoter and Business Strength
The lender first needs to understand who is behind the project.
Typical considerations may include:
Promoter experience
Industry knowledge
Existing business track record
Financial discipline
Existing borrowing
Repayment history
Credit profile
Existing business performance
Contribution toward the project
Management capability
A technically strong project can still face difficulties if the promoter lacks relevant experience or the business has weak financial controls.
For an established company, historical performance can provide valuable evidence of its ability to execute and manage a larger project.
2. Technical Feasibility
A lender needs confidence that the proposed project can actually be implemented.
Technical evaluation may cover:
Project location
Land availability
Plant layout
Machinery specifications
Production capacity
Technology
Raw-material availability
Utilities
Construction requirements
Implementation schedule
Vendor arrangements
Environmental and regulatory requirements
For a manufacturing project, for example, the lender may want to understand:
What will be produced?
How much can the plant produce?
What machinery is required?
Who will supply it?
How long will installation take?
When can commercial production begin?
These questions affect both the project cost and the projected cash flow.
3. Financial Viability
Financial viability is one of the most important components of project appraisal.
The lender wants to determine whether the project can generate adequate cash after accounting for operating expenses and debt obligations.
The financial model may include:
Projected revenue
Production volume
Selling price
Raw-material costs
Employee costs
Utilities
Administrative expenses
Maintenance
Taxes
Depreciation
Interest
Debt repayment
Working capital
Cash flow
A simple model might look like:
Projected Revenue
− Operating Expenses
= Operating Cash Generation
− Taxes
− Debt Service
= Cash Available After Debt Service
If the projected cash generation is weak, the lender may reduce the proposed debt, require additional promoter contribution or decline the project.
What Is DSCR and Why Does It Matter?
Debt Service Coverage Ratio (DSCR) is one of the important indicators lenders may use to evaluate repayment capacity.
A simplified concept is:
DSCR = Cash Available for Debt Service ÷ Debt Service Obligations
Suppose a project generates ₹4 crore of cash available for debt servicing and its annual debt obligations are ₹3 crore.
The simplified DSCR would be:
₹4 crore ÷ ₹3 crore = 1.33
A stronger coverage ratio generally provides greater repayment comfort.
However, there is no single DSCR number that automatically guarantees approval.
The acceptable level can vary depending on:
Lender policy
Industry
Project risk
Tenure
Security
Cash-flow stability
Promoter strength
Project structure
Businesses should therefore avoid designing a project around one ratio alone.
What Is Project Cost?
Before applying for project finance, the business needs a realistic estimate of the total project cost.
Depending on the project, this can include:
Land and Site Development
Land acquisition
Site preparation
Development work
Registration-related costs where applicable
Building and Civil Construction
Factory building
Warehouse
Office
Utility structures
Civil works
Machinery and Equipment
Main machinery
Supporting equipment
Installation
Transportation
Testing and commissioning
Technology
Technology acquisition
Software
Technical consultancy
Licensing where applicable
Pre-Operative Expenses
Depending on lender policy and project structure, certain eligible costs incurred before commercial operations may be considered.
Contingency
A realistic project budget should account for potential cost variations rather than assuming every estimate will remain unchanged.
Initial Working Capital
The project may need operating liquidity after the plant or facility becomes operational.
Underestimating this requirement can create a funding gap even after the project has been completed.
Why Promoter Contribution Matters
Project finance usually requires the promoter to have meaningful financial participation in the project.
This serves several purposes.
First, it reduces the amount that must be borrowed.
Second, it demonstrates the promoter's commitment to the project.
Third, it creates a financial buffer against cost overruns and delays.
For example:
Project Cost: ₹20 crore
If the promoter contributes ₹6 crore and debt contributes ₹14 crore, the project begins with a different financial structure than if almost the entire project were debt-funded.
The exact debt-equity or promoter-contribution structure depends on the lender, project type and credit assessment.
A promoter should therefore calculate the contribution requirement before finalizing the project plan.
Project Finance Eligibility in India
There is no single universal eligibility formula applicable to every project-finance application.
Eligibility depends on the lender and the specific project.
However, lenders commonly look for several broad characteristics.
Established or Credible Business Profile
An operating business with a demonstrated track record may have an advantage because its financial history provides evidence of performance.
Start-ups and new project entities can also potentially seek project funding, but the lender may require stronger evidence of promoter capability, project viability, capital contribution and execution readiness.
Relevant Promoter Experience
Industry experience can reduce execution risk.
A promoter setting up a project in an industry they understand may be easier to assess than a completely unrelated venture.
Acceptable Credit Profile
The business and relevant promoters generally need to demonstrate responsible borrowing behavior.
Credit history does not operate independently, but poor repayment history can materially affect lender confidence.
Adequate Promoter Contribution
The promoter must be financially positioned to contribute the required portion of project cost.
Viable Project Economics
The proposed project should demonstrate a credible path toward revenue generation and debt repayment.
Clear Documentation
Ownership, registrations, financial records, project estimates and other supporting documents need to be sufficiently clear for due diligence.
Documents Required for Project Finance
Documentation varies by lender and project type, but businesses should generally prepare a comprehensive project file.
Business and KYC Documents
Depending on the constitution of the business:
PAN
Identity and address documents
Business registration documents
Incorporation documents
Partnership deed, where applicable
Memorandum and Articles of Association, where applicable
Udyam registration, where applicable
GST registration
Relevant licences and registrations
Financial Documents
Commonly requested financial information can include:
Audited financial statements
Profit and loss statements
Balance sheets
Cash-flow statements
Income-tax returns
GST records
Bank statements
Existing loan statements
Details of current liabilities
The lender may also require projections for the proposed project.
Project Documents
These may include:
Detailed Project Report (DPR)
Project cost estimates
Projected financial statements
Projected cash flows
Machinery quotations
Supplier quotations
Construction estimates
Land documents
Lease documents, where applicable
Project implementation schedule
Technical reports
Market study
Customer or off-take information where relevant
Promoter Documents
Depending on the assessment:
Promoter profile
Experience details
Net-worth statement
Existing investment details
Credit information
Source of promoter contribution
The exact document checklist should always be confirmed with the prospective lender before submission.
What Is a Detailed Project Report?
A Detailed Project Report (DPR) is one of the most important documents for a project-finance proposal.
It translates the business idea into a structured investment and operating plan.
A strong DPR can cover:
Executive Summary
What is the project and why is it being established?
Promoter Profile
Who will execute and operate it?
Industry Analysis
What is the market environment?
Product or Service
What will the project sell?
Market Analysis
Who are the customers?
Who are the competitors?
What is the expected demand?
Technical Details
What technology, machinery and infrastructure are required?
Project Cost
How much will the project cost?
Means of Finance
How will the project be funded?
Implementation Schedule
When will construction, installation and commercial operations begin?
Revenue Projections
What sales are expected?
Operating Costs
What will it cost to operate the project?
Financial Projections
What are the expected profit and cash flows?
Debt Repayment
How will the project service the proposed debt?
The DPR should not be treated as a document created only to satisfy a lender.
It should function as the financial and operational blueprint for the project itself.
The Project Finance Lender Process
The process can vary, but a typical journey looks like this:
Step 1: Define the Project
Clearly establish:
Project purpose
Location
Capacity
Estimated cost
Timeline
Expected revenue
Step 2: Calculate Total Project Cost
Prepare realistic estimates for land, construction, machinery, installation, pre-operative expenses and initial working capital.
Step 3: Determine Promoter Contribution
Identify how much capital the promoter can genuinely contribute.
Step 4: Calculate Debt Requirement
The financing requirement should be based on the actual funding gap rather than an arbitrary loan amount.
Step 5: Prepare the DPR
Build a detailed project and financial model.
Step 6: Submit the Proposal
The lender receives the application and supporting documentation.
Step 7: Credit and Project Appraisal
The lender assesses the promoter, business, project, market, financial projections, repayment capacity and risks.
Step 8: Due Diligence
Depending on the project, due diligence can involve verification of:
Financial records
Property
Machinery
Project estimates
Legal documents
Regulatory approvals
Existing liabilities
Promoter contribution
Business assumptions
Step 9: Sanction
If the project is approved, the lender issues a sanction containing the applicable terms and conditions.
Step 10: Documentation and Security Creation
Required legal and security documentation is completed.
Step 11: Disbursement
Project finance is often disbursed according to the project's requirements and lender conditions rather than necessarily as one unrestricted lump sum.
Step 12: Project Implementation
Construction, procurement and installation begin.
Step 13: Commercial Operations
Once the project becomes operational, the business begins generating the projected revenue and cash flows.
Why Project Delays Can Create Financing Problems
A project can become financially stressed even when the original business plan was sound.
Suppose:
Project cost: ₹20 crore
Expected commercial operation: January
Actual operation: July
The business may face six additional months of:
Interest costs
Employee expenses
Construction costs
Administrative expenses
Working-capital requirements
while expected project revenue has not yet started.
This is why implementation schedules are an important part of project planning.
Businesses should build realistic timelines rather than assuming every project milestone will happen exactly as planned.
Cost Overruns: A Major Project-Finance Risk
Suppose the approved project cost is ₹30 crore.
During implementation, the actual cost rises to ₹34 crore.
The additional ₹4 crore must be funded somehow.
This creates a potential funding gap.
Cost overruns can arise from:
Construction delays
Machinery price increases
Currency movements for imported equipment
Design changes
Regulatory requirements
Transportation costs
Contractor issues
Unexpected site conditions
Promoters should therefore maintain contingency planning and avoid committing the entire available capital without considering unexpected costs.
What Can Cause a Project Finance Application to Be Rejected?
There is no single rejection reason.
Common concerns can include:
Weak Project Economics
Projected revenue or margins may not support the proposed debt.
Excessive Leverage
The business may already have substantial debt.
Insufficient Promoter Contribution
The promoter may not have adequate funds to support the proposed project structure.
Unrealistic Projections
Aggressive sales assumptions without supporting market evidence can reduce lender confidence.
Weak Credit History
Significant repayment issues can affect the credit assessment.
Poor Documentation
Missing or inconsistent information can delay or weaken the proposal.
Regulatory Uncertainty
Projects dependent on unresolved approvals or licences may carry greater execution risk.
Market Risk
A project entering an oversupplied or highly competitive market may face weaker revenue prospects.
Cost Underestimation
A project budget that ignores realistic implementation costs can create concerns about financial viability.
How to Improve Your Project Finance Proposal
A strong proposal is not simply a collection of documents.
It should tell a consistent financial story.
Make the Project Cost Defensible
Use credible quotations and realistic estimates.
Explain the Revenue Assumptions
Don't simply state:
"Revenue will grow 30% annually."
Explain why.
For example:
Production capacity
Expected utilization
Selling price
Customer pipeline
Existing contracts
Market demand
Show the Cash Flow
Profit is important, but debt is ultimately serviced through cash generation.
Clearly show how the project generates cash and when those cash flows begin.
Demonstrate Promoter Capability
Explain why the promoters are capable of executing the project.
Identify Risks
A proposal becomes more credible when it acknowledges potential risks and explains mitigation measures.
Keep Numbers Consistent
The project cost, debt requirement, promoter contribution, revenue projections and financial statements should all reconcile.
Project Finance and Working Capital Are Not the Same
One of the most important distinctions for business owners is between funding the project and funding its ongoing operations.
Project finance may fund:
Plant
Machinery
Construction
Infrastructure
Long-term project assets
Working capital finance may support:
Inventory
Receivables
Supplier payments
Operating expenses
Short-term cash-flow requirements
A new manufacturing facility may therefore require both:
Term/project finance for creating the facility
and
Working-capital finance for operating it after commissioning.
Failing to plan for the second requirement can leave an otherwise successful project short of operating liquidity.
Project Finance vs Machinery Finance
The two can overlap but are not identical.
Machinery finance primarily focuses on acquiring equipment.
Project finance looks at the broader investment.
For example:
A business purchasing a ₹3 crore machine may only require equipment financing.
A business establishing a ₹30 crore manufacturing unit may need financing for:
Land
Building
Machinery
Utilities
Installation
Pre-operative expenses
Initial working capital
The second situation requires a broader project assessment.
Should an Existing Business Take Project Finance?
An existing business can consider project finance when it has a clearly defined expansion or investment plan.
It may be particularly relevant when:
The investment is substantial.
The project has a long implementation period.
The asset will generate revenue over multiple years.
Existing cash reserves are insufficient.
The project requires structured long-term funding.
However, borrowing capacity should always be assessed against the company's existing obligations.
A profitable company can still overextend itself if the new project adds more debt than its future cash flows can support.
A Practical Project Finance Checklist
Before approaching a lender, an Indian business should be able to answer these questions:
Project
What exactly are we building or expanding?
Why is the project required?
What will it produce or generate?
Where will it be located?
Cost
What is the total project cost?
Are land, construction and machinery costs included?
Have installation and pre-operative expenses been considered?
Is there a contingency provision?
Funding
How much can the promoter contribute?
How much debt is required?
Is working capital also required after commissioning?
Is there any other funding source?
Revenue
Who will buy the product or service?
What is the expected selling price?
What utilization level is realistic?
How quickly can the project reach commercial operations?
Repayment
What cash flow will service the debt?
What happens if revenue is lower than projected?
Is there sufficient cash-flow coverage?
What are the existing business's debt obligations?
Risk
What could delay the project?
What could increase costs?
What regulatory approvals are required?
What happens if demand is lower than expected?
If these questions cannot be answered clearly, the project may not yet be ready for financing.
Final Verdict: What Makes a Project Finance Proposal Bankable?
Project finance is not simply about asking a lender for a large amount of money.
It is about demonstrating that the proposed investment is:
Technically feasible + commercially viable + financially sustainable + properly structured.
A strong project-finance proposal connects every major component:
Project Cost
↓
Promoter Contribution
↓
Debt Requirement
↓
Project Implementation
↓
Commercial Operations
↓
Revenue Generation
↓
Cash Flow
↓
Debt Repayment
For Indian businesses, the quality of the project report, financial projections, promoter contribution, documentation and repayment analysis can significantly influence how a lender evaluates the proposal.
The most important preparation step is therefore to understand the project economics before approaching the lender.
Don't begin with:
"How much project finance can I get?"
Begin with:
"How much does this project genuinely cost, how much can I contribute, how much debt can the project safely support, and how will that debt be repaid?"
That approach creates a much stronger foundation for project financing.